Teaching Kids Money at Home
Kwame Johnson
| 12-10-2026
 · News team
Financial education at home is often discussed in broad terms, but its real power lies in the small, repeated routines that quietly shape a child’s financial identity.
Beyond basic lessons like saving or budgeting, everyday family behaviors establish deep-rooted attitudes toward risk, consumption, discipline, and long-term thinking. These patterns, once formed, tend to persist well into adulthood.
The Hidden Curriculum of Daily Life
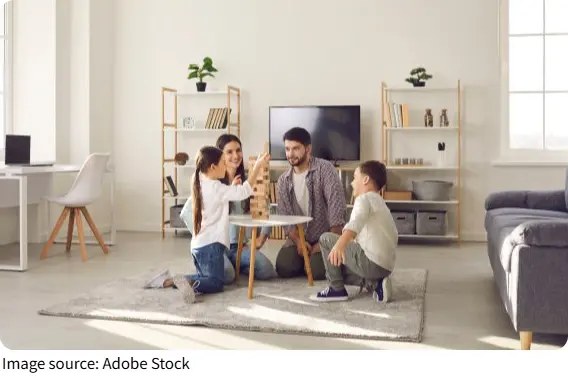
Children absorb financial norms through observation long before they understand financial concepts. What matters is not isolated “teachable moments,” but consistent exposure to how money is handled in real contexts: how decisions are made, how trade-offs are justified, and how priorities are set.
Should we edit human DNA? The ethical questions are more complex than you think!
A new way to see DNA! Nature-inspired forms bring it to life!
Can AI reshape genes? Science is entering a whole new era of possibilities!
Can bites spread disease? Yes! Smart prevention helps protect you daily!
The Investment Strategy Couples Never Talk About — And Why It’s Costing Them Wealth
Turning idle savings into steady growth—simple principles behind long-term wealth building
For example, when parents consistently evaluate purchases based on long-term value rather than short-term satisfaction, children internalize a framework for decision-making that goes beyond price. They begin to associate money with judgment, not just transactions.
Routine Spending as a Lesson in Opportunity Cost
Everyday spending decisions, especially recurring ones, offer a subtle but powerful way to teach opportunity cost. When a family chooses between dining out and saving for a larger goal, the reasoning behind that choice matters more than the outcome itself.
Explaining why one option is prioritized over another introduces children to the idea that money is a tool with competing uses. Over time, this develops an internal habit of evaluating alternatives rather than acting on impulse.
Structuring Allowances to Reflect Economic Reality
Allowances, when designed thoughtfully, can move beyond basic money management and simulate real financial systems. Instead of simply giving children money, families can introduce structured allocations, dividing funds into categories such as spending, saving, and giving.
This approach mirrors real-world financial planning and helps children understand constraints. It also introduces the concept of scarcity: once a category is depleted, no additional funds are available. This limitation encourages foresight and prioritization, two skills essential for long-term financial stability.
Family Decision-Making as Financial Training
Involving children in selected family financial decisions, such as planning a vacation budget or comparing major purchases, exposes them to multi-layered thinking. These discussions reveal how factors like timing, trade-offs, and long-term goals interact.
Rather than simplifying decisions for children, allowing them to see the complexity helps build analytical thinking. They begin to understand that financial choices are rarely binary and often involve balancing competing priorities.
Behavioral Modeling and Emotional Associations
Financial habits are not purely logical; they are deeply tied to emotions. The way parents react to financial stress, unexpected expenses, or financial success shapes how children emotionally relate to money.
If financial setbacks are handled with calm problem-solving, children are more likely to view challenges as manageable. Conversely, if money is associated with anxiety or avoidance, those emotional patterns can become ingrained. This emotional dimension is often overlooked, yet it plays a critical role in shaping long-term financial behavior, including risk tolerance and resilience.
Delayed Gratification in a Real Context
While delayed gratification is often taught as a concept, family routines provide a practical framework for experiencing it. Saving over time for a meaningful purchase, rather than spending immediately, creates a tangible link between patience and reward.
The key is consistency. When children repeatedly experience the benefits of waiting, they begin to value long-term outcomes over short-term impulses, a habit that supports sound financial choices later in life.
Expert Perspective: The Long-Term Impact
Annamaria Lusardi, an economist at Stanford University and a leading researcher in financial literacy, found in a study of young adults with Olivia Mitchell and Vilsa Curto that financial literacy is strongly related to the family’s financial sophistication.
In that study, fewer than one-third of young adults understood basic concepts such as interest rates, inflation, and risk diversification. The finding supports a critical point: financial education is not a one-time intervention but a cumulative process shaped by environment and repetition.
Ultimately, teaching money values through family routines is less about instruction and more about example. Children learn most effectively when what they observe matches what they are told.
A practical way to start is to pick one routine, such as explaining a regular spending choice aloud or dividing an allowance into categories, and keep it going. Over time, these routines build a durable financial mindset that supports stability, independence, and informed decision-making.