Green Household Gains
Elena Rossi
| 14-10-2026
 · News team
Hello Lykkers! When people hear “green lifestyle,” they often think about recycling bins, reusable bags, or energy-saving light bulbs. But sustainability is becoming much more than an environmental choice; it is increasingly a financial strategy.
Many households are discovering that greener habits can also mean better budgeting, lower expenses, and stronger long-term financial planning. The idea is simple: using resources more efficiently often means spending less. Over time, those small changes can create meaningful financial impact.
Lower Consumption, Lower Costs
One of the biggest financial benefits of a green lifestyle is reduced consumption. Sustainable living encourages households to use energy, water, and products more efficiently.
Can kids understand money? The right approach makes it possible!
A high dividend yield can look attractive, but the history behind that payment may tell you much more than the percentage alone.
The Hidden Family Wealth Code That Turns Ordinary Money Into Generational Power!
The Real Estate Truth Nobody Talks About: Slow Growth Often Wins Bigger!
Uncertain times causing stress? Simple strategies can help protect assets!
Examining Whether Property Truly Offers Stable Returns
Simple changes, such as energy-efficient appliances, reducing waste, or improving home insulation, can lower monthly utility bills. While some upgrades may require initial spending, the long-term savings often outweigh the upfront costs.
This shifts household finance from reactive spending to proactive planning. Instead of paying higher costs later, families invest in efficiency earlier.
Budgeting Through Sustainable Choices
Green living often encourages more intentional purchasing habits. Rather than frequent replacements, households may prioritize durability, repairability, and long-term value.
This mindset naturally supports stronger budgeting practices.
For example, buying a higher-quality product with a longer lifespan may reduce replacement costs over time. Similarly, meal planning and reducing food waste can improve household cash flow while cutting unnecessary spending.
Sustainability, in this sense, becomes closely linked with financial discipline.
Expert Perspective on Sustainable Living
Inger Andersen, Executive Director of the United Nations Environment Program, has emphasized the importance of using natural resources more sustainably and efficiently. UNEP describes sustainable consumption as doing “more and better with less,” including reducing resource use, waste, and environmental impacts while maintaining quality of life.
This principle applies directly to everyday choices. Using energy efficiently, reducing unnecessary consumption, extending product lifespans, and minimizing waste can reduce environmental pressure while also lowering certain household costs.
Energy Independence and Financial Stability
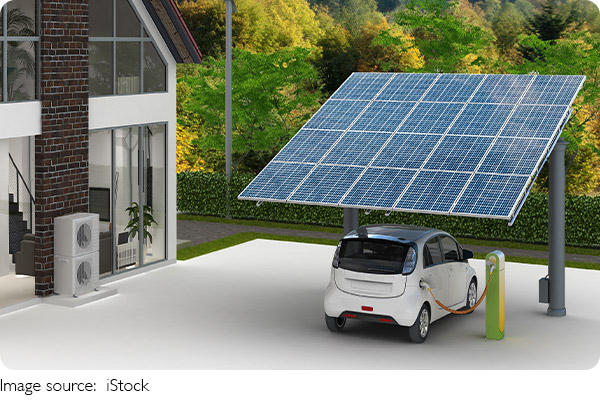
Many households are also exploring renewable energy solutions such as rooftop solar systems or energy-efficient home technologies.
While these investments may require upfront capital, they can reduce dependence on fluctuating utility prices. This creates more predictable monthly expenses, which is valuable for long-term financial planning.
Stable expenses make it easier to budget, save, and manage future goals.
In financial terms, sustainability can act as a buffer against uncertainty.
Reducing Waste Improves Cash Flow
Household waste is not just an environmental issue; it is often a financial one.
Unused food, excessive energy use, and unnecessary purchases all represent money leaving the household budget without adding value.
Green lifestyles encourage tracking consumption and minimizing waste. This improves efficiency and frees up resources for savings, investments, or emergency funds.
Even modest improvements can accumulate significantly over several years.
Long-Term Wealth Building Through Sustainable Habits
Sustainable living also aligns well with long-term wealth strategies. Lower expenses increase savings potential. Better energy management reduces operating costs. Durable purchases limit repeated spending.
Together, these changes improve financial flexibility.
Instead of viewing sustainability as an extra cost, many households are beginning to see it as an investment in future stability.
The goal is not simply to spend less—it is to spend smarter.
Teaching Financial Awareness at Home
Green lifestyles often involve household participation, making them valuable for financial education as well.
Children and family members learn about budgeting, resource use, and long-term planning through everyday decisions. These habits can shape stronger financial behavior over time.
Small actions- saving energy, reducing waste, planning purchases—become lessons in economic responsibility.
Conclusion
Green lifestyles are no longer only about environmental awareness. For many families, they are becoming a practical tool for household financial planning.
For Lykkers, the takeaway is simple: sustainability and finance are increasingly connected. Lower waste, smarter consumption, and efficient living do more than support the environment; they can help build stronger financial foundations for the future.